01
What a Giveback plan actually is
It's a Medicare Advantage benefit that gives back part of your Part B premium. We break down exactly how the Part B reduction works — in plain language, not jargon.
Criselda Hernandez
My Insurance Specialist · Licensed Agent
A free, plain-English webinar on the Part B giveback benefit — what it really is, what it costs you somewhere else, and how to tell if it's the right fit for your doctors, your prescriptions, and your budget.
Reserve your seat
Live sessions every day at 9:00 AM & 5:00 PM ET. Pick a time, enter your details, and you'll go straight to the live room.
$202.90
2026 standard Part B premium
120 days
max wait for the giveback to appear
Oct 15–Dec 7
Annual Enrollment Period
6 yrs
helping families navigate Medicare
What you'll learn
01
It's a Medicare Advantage benefit that gives back part of your Part B premium. We break down exactly how the Part B reduction works — in plain language, not jargon.
02
On Original Medicare or a supplement? The Giveback won't apply. On full Medicaid or an employer-paid Part B? There's nothing to give back. Find out if you even qualify.
03
The benefit isn't free — plans offset it with higher copays, bigger deductibles, less dental or vision. We show you how to weigh the trade-offs before you switch.
04
Every MA plan has a different network and drug formulary. Learn the questions to ask your agent so your specialists and prescriptions stay covered and affordable.
05
Read your Summary of Benefits and Evidence of Coverage. Compare them against what an agent promised so the numbers line up before January 1st.
06
Annual Enrollment runs Oct 15–Dec 7. Plans hit area caps and close to new enrollees — waiting until the last day can mean missing the plan you wanted.
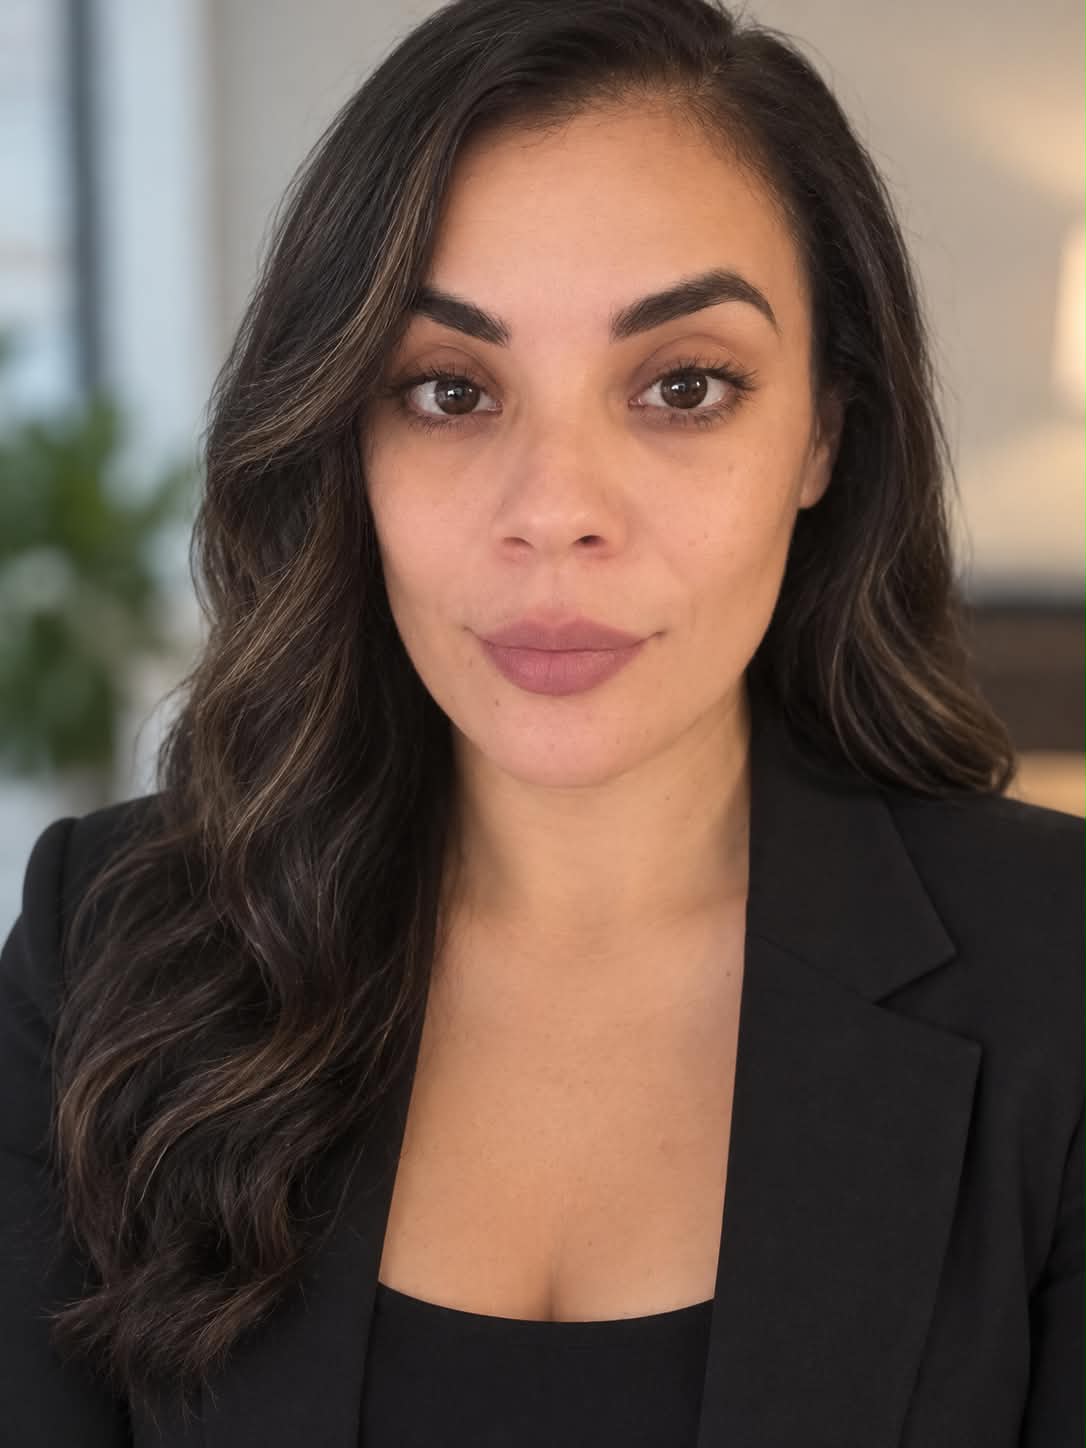
Criselda "Chris" Hernandez
My Insurance Specialist · Licensed Agent
Your host
Six years ago I was power of attorney for my grandma — pacemaker, diabetes, a bad knee, a whole roster of doctors. She got a phone call, somebody changed her to a plan with a very shiny benefit, and when we actually used it, none of her doctors were in network. Right in the middle of procedures.
That's when I learned — the hard way — that people actually pay for Medicare, that benefits get moved around, and that a flashy giveback can quietly cost you the care you need. Now I help families ask the right questions before they switch.
I get paid by the insurance company, not you. It doesn't matter to me which carrier you pick — what matters is that you understand your benefits and can actually use them.
Frequently asked
No. It's a reduction of your Part B premium that shows up on your Social Security check — not a separate payment or guarantee of free healthcare. It's still a regular Medicare Advantage plan with copays and rules.
No. The Giveback benefit is part of Medicare Advantage plans only. If you're on Original Medicare or a supplement, this particular benefit doesn't apply to you.
Then there's nothing to give back — the state is already covering it, so you're getting the full benefit. The Giveback only helps people who are paying their own Part B premium.
It can take up to 120 days to process — often around a three-month window. You'll get the full amount for all the back months once it kicks in, so don't expect it January 1st.
No. This is an educational event by a licensed independent health insurance agent. I'm not connected to or endorsed by the US government or any federal program. I don't offer every plan in every area — what I can show you depends on your zip code and county.
Nothing — the insurance company pays me, not you. I do a needs analysis (your doctors, prescriptions, how often you see specialists, what you need this year) and we go over your options together.
Register for the live webinar, ask questions in the chat, then book a quick call. We'll check your zip code, your doctors, your prescriptions — and only recommend a switch if it actually makes sense for you.
Reserve My Seat →